Overview
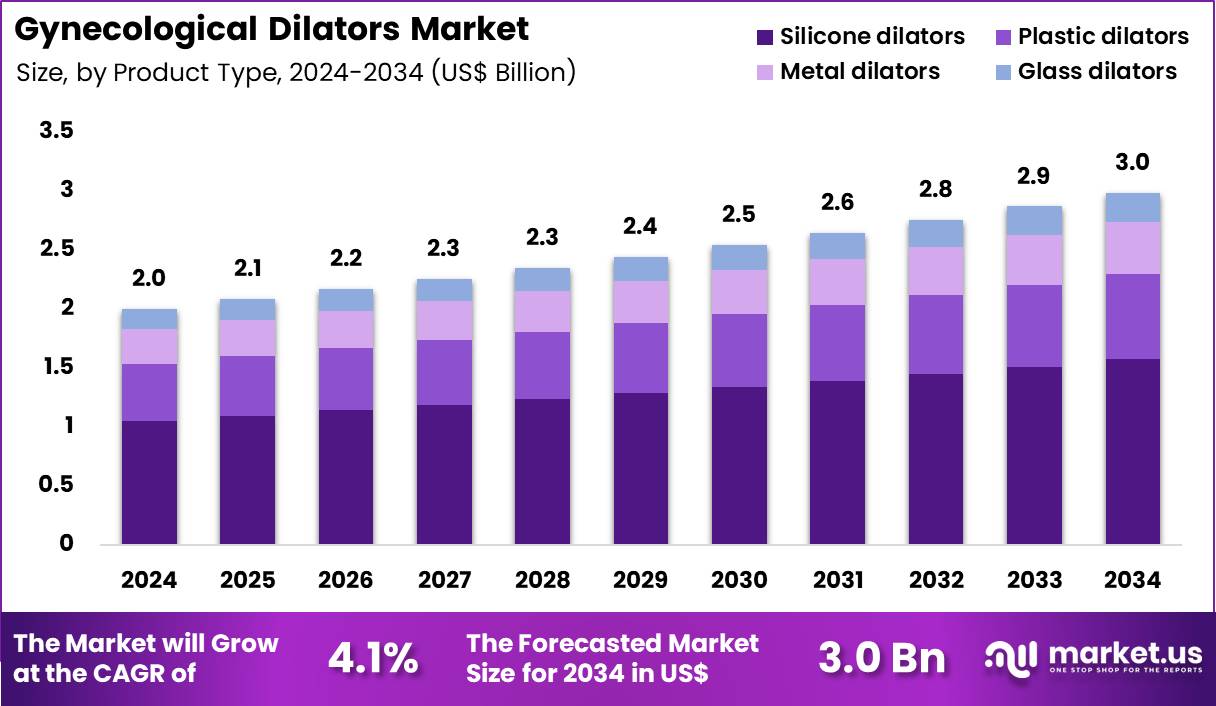
New York, NY – Oct 05, 2026 – The Global Gynecological Dilators Market size is expected to be worth around US$ 3.0 Bllion by 2034 from US$ 2.0 Billion in 2024, growing at a CAGR of 4.1% during the forecast period 2025 to 2034. In 2024, North America led the market, achieving over 42.8% share with a revenue of US$ 0.9 Billion.
Gynecological dilators are medical devices designed to gently widen or maintain the vaginal canal. They are used in various gynecological and therapeutic applications, including treatment of vaginal narrowing, pelvic floor conditions, post-surgical care, and certain procedures requiring controlled vaginal access. These devices are available in different sizes and materials, allowing healthcare professionals to select products based on individual patient requirements.
The global gynecological dilators market is being supported by increasing awareness of women’s health, growing demand for minimally invasive treatment options, and improved access to specialized gynecological care. Rising attention toward pelvic health and sexual wellness is also contributing to greater awareness and adoption of these devices.
Technological developments are encouraging manufacturers to focus on patient comfort, ergonomic designs, smooth surfaces, flexible materials, and improved usability. Reusable and single-use product options are available across healthcare settings, depending on clinical requirements and infection-control practices.
North America and Europe remain important markets due to established healthcare systems and higher awareness of specialized women’s healthcare products. Meanwhile, Asia-Pacific is expected to offer growth opportunities as healthcare infrastructure expands and awareness of gynecological health increases.
Market participants are focusing on product innovation, distribution expansion, regulatory compliance, and improved patient-centric designs to strengthen their market positions. Continued advances in women’s healthcare are expected to support the long-term development of the gynecological dilators market.
Key Takeaways
- In 2024, the market generated US$ 2.0 billion in revenue and is projected to reach US$ 3.0 billion by 2034, expanding at a CAGR of 4.1% during the forecast period.
- By product type, the market is segmented into silicone dilators, plastic dilators, metal dilators, and glass dilators. Among these, silicone dilators dominated the market in 2023, accounting for a 52.6% share.
- By size, the market is categorized into medium, small, large, and customizable size dilators. The medium dilators segment held the leading position, accounting for 41.9% of the market.
- By application, the market is divided into medical and personal segments. The medical segment dominated the market, representing the largest revenue share of 68.4%.
- By distribution channel, the market is segmented into hospitals & clinics, online retailers, medical supply stores, and pharmacies. Hospitals & clinics accounted for the largest revenue share of 46.8%.
- By consumer type, the market is segmented into healthcare professionals, caregivers, patients undergoing treatment, and individuals seeking personal care solutions. Healthcare professionals held the largest share at 44.7%.
- Regionally, North America dominated the market in 2024, accounting for a significant 42.8% market share.
Key Market Segments
- Product Type Analysis: Silicone dilators lead the gynecological dilators market with a 52.6% share, supported by their softness, flexibility, comfort, and biocompatibility. Their low irritation risk, easy sterilization, and suitability for repeated use make them preferred for clinical, post-surgical, and rehabilitation applications.
- Size Analysis: Medium-sized dilators account for a 41.9% share, reflecting their broad use across different treatment stages. Their balanced flexibility and rigidity allow gradual dilation with improved comfort. Clinicians commonly prefer medium sizes because they support treatment progression, patient tolerance, and efficient inventory management.
- Application Analysis: Medical applications dominate the gynecological dilators market with a 68.4% share, supported by increasing use in post-surgical, post-radiation, and vaginal stenosis management. Physician supervision, structured treatment protocols, and growing rehabilitation needs among gynecological cancer survivors continue to strengthen medical demand.
- Distribution Channel Analysis: Hospitals and clinics represent the leading distribution channel, accounting for a 46.8% share. These facilities commonly initiate and monitor dilator therapy, supported by professional guidance, centralized procurement, quality controls, and structured rehabilitation programs. Institutional trust further strengthens product adoption and demand.
- Consumer Type Analysis: Healthcare professionals represent the largest consumer group, accounting for a 44.7% share. Gynecologists, pelvic health specialists, and rehabilitation teams influence product selection, size progression, and treatment duration. Professional supervision supports correct usage, patient safety, treatment adherence, and continued adoption across healthcare settings.
Regional Analysis
North America held a 42.8% share of the global gynecological dilators market in 2024, supported by growing demand for minimally invasive women’s healthcare procedures, improved product designs, and increasing use of disposable and graduated dilators.
Rising cases of gynecological conditions, preventive healthcare initiatives, and greater awareness of pelvic health are supporting demand.
Hospitals and ambulatory surgical centers are increasingly adopting sterile, single-use products to strengthen infection control. Regulatory approvals for biocompatible materials and advancements in ergonomic designs are also supporting product adoption across clinical applications.
Asia Pacific is expected to register the highest CAGR during the forecast period, driven by expanding reproductive healthcare programs, improving medical infrastructure, and rising awareness of women’s health.
Increasing gynecological procedures, fertility treatments, and cervical cancer screening are creating demand for reliable dilation devices. Government healthcare initiatives, growing hospital investments, and product innovations are further supporting regional expansion.
Rising healthcare access across emerging economies is expected to create significant opportunities for manufacturers.
Emerging Trends
- Growing adoption of video laryngoscopes: Video laryngoscopy is becoming an important alternative to traditional direct laryngoscopy. These devices use a camera and display to provide a view of the vocal cords, which can make airway visualization easier. A 2024 meta-analysis of emergency intubations found higher first-attempt success with video laryngoscopy compared.
- Development of compact and portable devices: Manufacturers are increasingly focusing on equipment that can be used outside the operating room, including emergency departments, intensive-care units, ambulances, and other critical-care environments. This trend is supported by evidence on video laryngoscopy in out-of-hospital intubation, where studies have examined its use by physicians, nurses, and paramedics.
- Greater focus on difficult-airway management: Laryngoscope development is increasingly centered on improving visibility in patients where conventional intubation can be difficult. Recent clinical reviews report that several video laryngoscope designs can improve the laryngeal view and, in some settings, first-pass success.
- Standardization and regulatory focus on video technology: The regulatory environment is also adapting to video laryngoscopy. In 2025, the U.S. FDA recognized ISO 7376-2:2025, which specifies requirements for electrically powered video laryngoscopes, including the handle, rigid blade, light source, camera, and image display. This indicates increasing standardization of video-enabled airway devices.
- Increasing focus on measurable clinical outcomes: Research and product evaluation are increasingly concentrating on measurable outcomes such as first-pass success, intubation time, glottic view, complications, and esophageal intubation. A recent systematic review of critically ill adults reported improved first-attempt success with video laryngoscopy, although the authors noted substantial variation between studies and limited certainty for some outcomes.
Use Cases
- Endotracheal intubation during surgery: Laryngoscopes are widely used to visualize the airway and guide placement of an endotracheal tube during general anesthesia. Both direct and video laryngoscopes are used depending on the patient, procedure, and clinical setting.
- Emergency airway management: Laryngoscopes are used when rapid airway control is required, including serious trauma, respiratory failure, and other emergencies. Evidence from emergency-intubation studies indicates that video laryngoscopy can improve first-attempt success in several emergency settings.
- Pre-hospital and ambulance services: Portable laryngoscopes are used by emergency medical teams for airway management before a patient reaches a hospital. A systematic review covering 25 studies and 35,489 out-of-hospital intubations found that video laryngoscopy was associated with improved first-pass success in several clinician groups, although substantial differences existed between studies.
- Cardiac arrest and resuscitation: Laryngoscopes can be used to establish an advanced airway during cardiopulmonary resuscitation. However, recent ILCOR-supported evidence found that while video laryngoscopy may improve some process measures, there is currently no evidence that it improves return of spontaneous circulation or survival compared with direct laryngoscopy during cardiac arrest.
Frequently Asked Questions About Gynecological Dilators
- What factors are driving the gynecological dilators market?
Market growth is supported by increasing awareness of pelvic health, greater attention to women’s healthcare, rising adoption of minimally invasive supportive therapies, and expanding access to specialized gynecological products across hospitals, clinics, and home-care settings. - Which region dominates the gynecological dilators market?
North America has represented a significant market for gynecological dilators because of established healthcare infrastructure, awareness of women’s health, product availability, and adoption of specialized pelvic health therapies. Europe and Asia-Pacific also present growth opportunities. - How is the gynecological dilators market segmented?
Major market segments can be classified by product type, material, application, end user, and distribution channel. Common end users include hospitals, specialty clinics, rehabilitation centers, and individual consumers purchasing products through pharmacies or online platforms. - Which materials are commonly used in gynecological dilators?
Silicone and other medical-grade materials are gaining attention because they can provide flexibility, durability, and compatibility with repeated use. Material selection remains influenced by clinical requirements, user comfort, manufacturing standards, cleaning needs, and product positioning. - What role do online sales channels play in the market?
Online channels are becoming increasingly important for gynecological dilator distribution because they can improve product accessibility, provide privacy, and expand geographic reach. Pharmacies, specialty retailers, hospitals, and clinics continue to contribute substantially to overall distribution. - What regulatory factors affect the gynecological dilators market?
Regulatory requirements vary by country and depend on the intended use and classification of the product. Manufacturers generally need to address applicable safety, quality, labeling, manufacturing, and market authorization requirements before commercial distribution. - What factors influence demand for gynecological dilators?
Market demand can be influenced by healthcare spending, awareness of pelvic disorders, treatment rates for conditions associated with vaginal narrowing, availability of trained professionals, consumer purchasing behavior, and acceptance of home-based pelvic health management. - What is the future outlook for the gynecological dilators market?
Future market development is expected to be influenced by product innovation, improved awareness of women’s pelvic health, expanding digital commerce, broader healthcare access, and increasing emphasis on personalized treatment. Competitive intensity is also expected to remain significant.
Conclusion
The global gynecological dilators market is expected to witness steady growth, supported by increasing awareness of women’s health, rising demand for minimally invasive therapies, and expanding access to specialized gynecological care.
Silicone dilators are expected to remain prominent due to their flexibility, comfort, and biocompatibility, while medical applications and hospital-based distribution will continue to account for significant demand. North America currently leads the market, supported by established healthcare infrastructure, whereas Asia-Pacific is expected to experience faster growth.
Product innovation, patient-centric designs, online distribution, regulatory compliance, and expanding pelvic health awareness are likely to create further opportunities for market participants through 2034.
Discuss your needs with our analyst
Please share your requirements with more details so our analyst can check if they can solve your problem(s)